Introduction
Foreign investors who own property in Malaysia should also understand the tax consequences of selling it. While foreign purchasers mainly deal with stamp duty, foreign vendors (sellers) must deal with Real Property Gains Tax (“RPGT”) and the retention sum (part of the sale price held back to cover the seller’s RPGT) under the Real Property Gains Tax Act 1976.
This article explains how RPGT applies to foreign vendors, and what the retention sum means in practice for both vendors and purchasers.
For the taxes and costs that apply when a foreigner buys property, see our article Buying Property in Malaysia as a Foreigner: Stamp Duty and Costs. For quit rent, assessment and a summary checklist of all the taxes involved, see Quit Rent, Assessment and a Tax Checklist for Foreign Property Owners in Malaysia.
Taxes Applicable to Foreign Vendors
A. Real Property Gains Tax (RPGT)
When a foreigner sells or otherwise disposes of Malaysian property, they are subject to RPGT, which is imposed under the Real Property Gains Tax Act 1976. Unlike stamp duty, RPGT is imposed on the vendor, not the purchaser. It is charged on the profit (gain) made from the disposal.
RPGT Rates for Foreign Individuals
| Disposal Period | RPGT Rate |
|---|---|
| Within 5 years | 30% |
| 6th year onwards | 10% |
B. RPGT Retention Sum
When a foreign vendor sells property, perhaps the most important practical issue is the retention sum required by law.
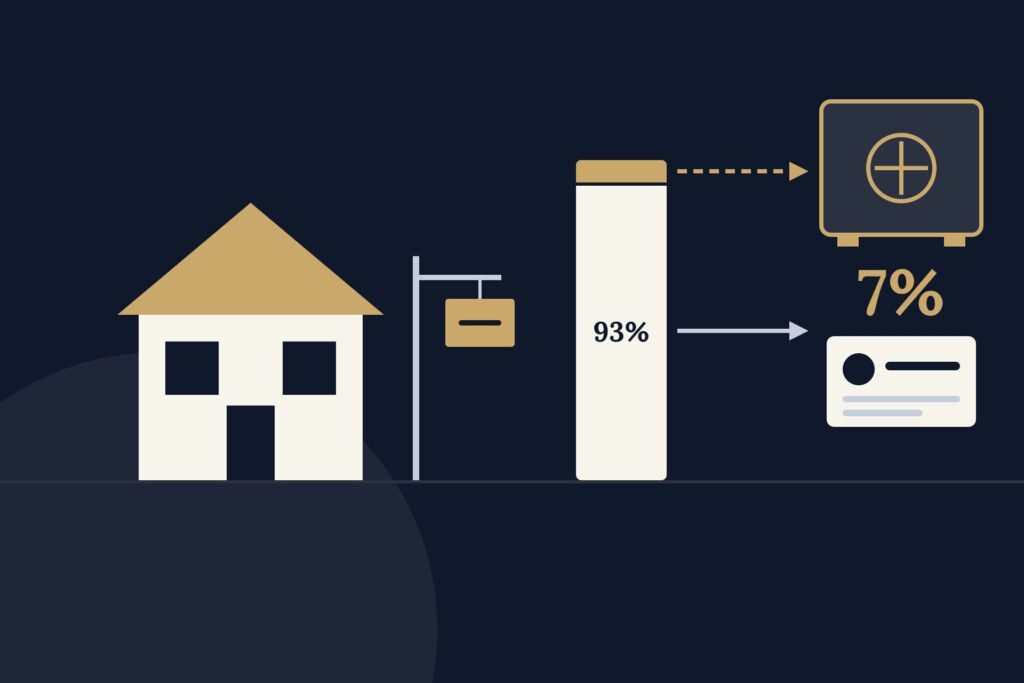
Under Section 21B of the Real Property Gains Tax Act 1976, where the vendor is a foreigner, the purchaser or the purchaser’s solicitor must hold back 7% of the purchase price and pay it to the Director General of Inland Revenue (“DGIR”) within the time limit set by law.
The retained amount serves as security for the vendor’s RPGT liability. Once the DGIR has assessed the RPGT payable:
- any amount held back beyond the tax due will be refunded to the vendor; or
- if the retention sum is not enough to cover the RPGT due, the vendor must pay the balance.
Purchasers and their solicitors should therefore strictly comply with Section 21B to avoid penalties for late payment or non-compliance.
Conclusion
Foreign vendors should keep in mind that they may have to pay RPGT when they sell, at 30% if the property is disposed of within 5 years and 10% from the 6th year onwards, and that 7% of the purchase price must be held back by the purchaser’s solicitors and paid to the DGIR.
Because the tax position depends on the facts of each sale, including the holding period, foreign vendors should get independent legal advice before selling their property.
Have a question on a related matter? Reach out to our partner.
Get in touch